TorontoReverseMortgage.ca covers how a reverse mortgage in East York works for homeowners 55 and older. East York is the former Borough of East York, formed in 1967 when the Town of Leaside joined East York Township, and part of the City of Toronto since 1998.
It lies north of Danforth Avenue, between the Don River and Victoria Park Avenue, next to Old Toronto, North York and Scarborough. Its homes range from 1940s bungalows to Leaside houses worth more than $2 million.
East York’s homes and what they mean for a reverse mortgage
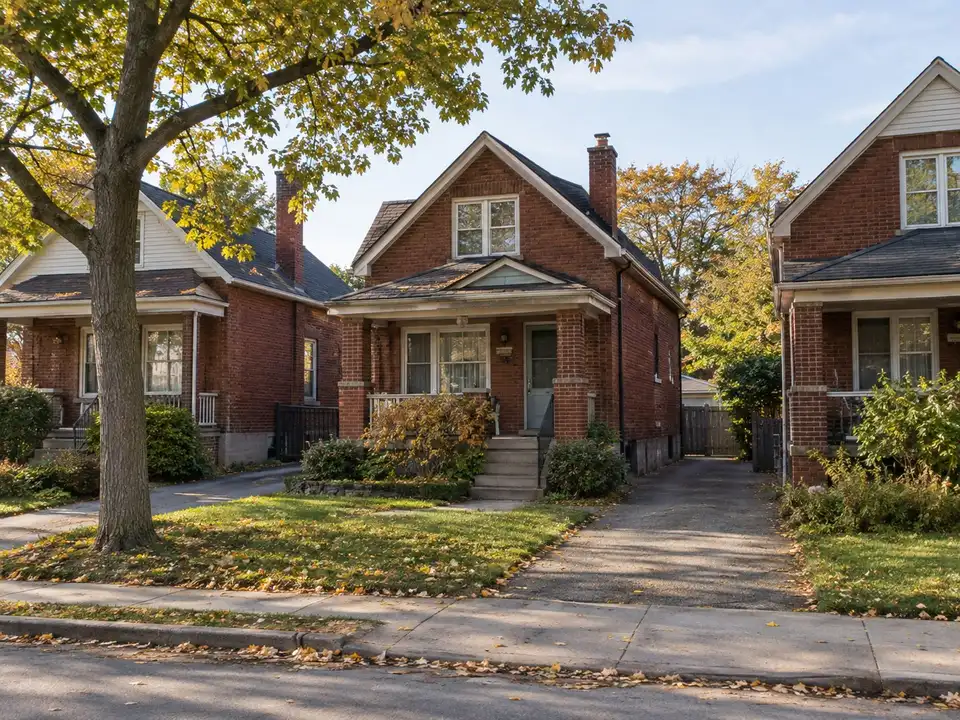
East York’s core is 1940s housing. After the Second World War, inexpensive homes were built for returning veterans and their families, including the streets around Topham Park. Most were single detached houses with front yards and back gardens, and many of the original one-storey bungalows have since added second floors.
About 48.8% of East York’s homes were built in 1960 or earlier, the highest of Toronto’s six former cities. That 2021 Census figure groups the City’s neighbourhood profiles by the old borders, so treat it as a close estimate (City of Toronto Neighbourhood Profiles, 2021 Census).
For a reverse mortgage, the condition of an older house is part of approval. A booked repair can sometimes be built in with a holdback, money set aside until the repair is finished. A house in serious disrepair may need repairs first.
TRREB reports prices by district, and no district matches East York. The two closest each include a neighbourhood from next door: Danforth and Playter Estates (Old Toronto) are in E03, and Flemingdon Park (North York) is in C11. Any East York price is an approximation for that reason.
The gap between those two districts is large. In September 2026, E03’s detached benchmark (TRREB’s price for a typical house) was $1,171,800, and C11’s was $2,174,100, almost twice as much (TRREB Market Watch, September 2026).
Leaside and Thorncliffe Park
Leaside and Thorncliffe Park are neighbours in C11, with very different homes. Leaside was laid out in 1912 as a planned company town for the Canadian Northern Railway, and it is mostly single-family houses.
Thorncliffe Park, on a former racetrack, was built with 30 mid-rise and high-rise rental apartment buildings from the 1960s into the early 1970s. Only owners can take a reverse mortgage, so a tenant in one of those towers can’t get one, while a condo unit you own can qualify.
In C11, the detached benchmark of $2,174,100 was more than five times the condo apartment benchmark of $409,600. At the same age, a house at that benchmark could provide about five times as much as a condo at its benchmark.
Who asks about reverse mortgages in East York
East York was long home to many seniors, as the original 1940s owners grew older. That has shifted: about 15.2% of residents were 65 or older in 2021, below the city-wide 16.5%, on the same close-estimate basis (City of Toronto Neighbourhood Profiles, 2021 Census).
More than half of East York owners, about 56.4% on the same basis, still had a mortgage in 2021. A payment that fit a working income can be hard to keep up on a pension, and a reverse mortgage can pay off a mortgage in retirement with no required monthly mortgage payments afterward.
Other questions start with the house or the family. An older house may need a roof, windows or a main-floor bathroom to stay safe, which is where aging-in-place renovations come in.
Some owners want to help a child buy nearby while they can see the help used. On streets where neighbours are adding second storeys, a long-time owner may simply want to stay.
A worked example: a 1940s bungalow in East York at $1,171,800
For example, an illustrative widow, aged 75, has owned her 1940s bungalow north of the Danforth for decades, with no mortgage left. It is valued at $1,171,800, TRREB’s September 2026 detached benchmark for E03. At 75, she could borrow up to about 58% of the value, or about $676,700.
She wants to stay on her street while it changes around her. She takes $70,000 to add a main-floor bathroom and a ramp to the front door, so she can live on one floor as she gets older. The other $606,700 or so stays untouched, and interest is charged only on the $70,000 she took.
She has no required monthly mortgage payments, but her property taxes, home insurance and upkeep are still hers to pay. Interest adds to the $70,000 over time, but home price growth often offsets some or all of it, and Canadian borrowers keep about half their equity on average.
East York neighbourhoods and landmarks
Help is the same in every part of East York. These are some of the neighbourhoods and places it covers.
- Leaside
- Bennington Heights
- Thorncliffe Park
- Topham Park
- O'Connor-Parkview
- Woodbine-Lumsden
- Crescent Town
- Broadview North
- Old East York
Landmarks
- East York Civic Centre
- Michael Garron Hospital
- Todmorden Mills
- Crothers Woods
- East York Town Centre
- Leaside station on Line 5 Eglinton
How the help reaches you in East York
Richard Hopkins, Mortgage Broker, helps East York homeowners by email, phone and video call, and family members can join a three-way call. An appraiser visits the home. For the in-person appointment with your own lawyer, Line 5 Eglinton stops at Leaside station, and the Line 2 stations along Danforth Avenue are just south of East York.
What East York homes are worth right now
TRREB does not report East York as one area, so these numbers use its two closest districts as an approximation: E03, which also includes Danforth and Playter Estates in Old Toronto, and C11, which also includes Flemingdon Park in North York. In September 2026, the detached benchmark (TRREB's price for a typical house) was $1,171,800 in E03 and $2,174,100 in C11, and the condo apartment benchmark was $453,500 and $409,600. At 65, up to 50.55% of the value means about $592,300 on an E03 house and about $1,099,000 on a C11 house; at 75, up to 57.75% means about $676,700 and about $1,255,500.
Source: TRREB Market Watch, September 2026 (MLS® Home Price Index benchmarks)
How East York homeowners use a reverse mortgage
- Renovations to stay at home: A walk-in shower, grab bars or a stair lift, paid for from your home's value so you can stay where you are.
- Helping your children buy a home: Give part of an inheritance now, while you can see it help, and keep living in your own home.
- Clearing debts: A reverse mortgage can clear cards, lines of credit and property tax arrears, with no required monthly mortgage payments afterward.
- Paying off your mortgage: When a renewal no longer fits a retirement income, a reverse mortgage can pay off what you owe and end the monthly mortgage payment.