TorontoReverseMortgage.ca shows what a reverse mortgage in Scarborough can do for homeowners 55 and older who want to stay in the house they own.
The challenge in Scarborough is not usually the house. It is the income. A detached house here has a TRREB benchmark of $861,700 to $1,081,100, while Toronto residents 65 and older had a median after-tax income of $30,000 in 2020 (City of Toronto).
This page uses TRREB’s September 2026 figures for Scarborough’s own districts, E04 to E11, and 2021 Census data for its wards and neighbourhoods.
Scarborough’s homes and what they mean for a reverse mortgage
Most of Scarborough was built after the Second World War. It became a borough in 1967 and developed quickly as a suburb over the next decade, as much of its farmland turned into subdivisions (Wikipedia).
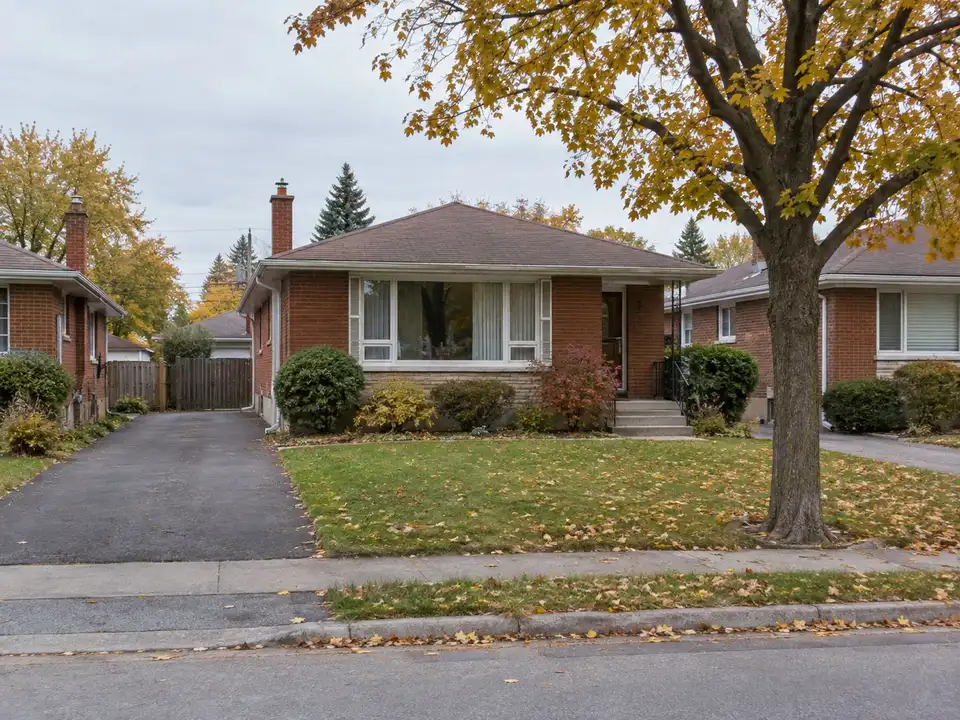
The south and centre are the oldest parts. In Ward 21 (Scarborough Centre), 56% of people in detached houses live in one built from 1946 to 1960 (City of Toronto Ward Profiles). Wexford is mostly post-war bungalows (Wikipedia).
The north-east is newer: in Ward 25 (Scarborough-Rouge Park), 54% live in houses built from 1981 to 2005.
Brick bungalows, backsplits and sidesplits on wide lots line many of the older streets. Scarborough also has the most single-detached houses, as a share of all homes, of Toronto’s six former municipalities: 37.2% in 2021 (counted from the City’s neighbourhood data).
Scarborough has the lowest average price of the six. Across TRREB districts E04 to E11, homes of all types sold for an average of $802,360 from January to September 2026. In September, detached houses averaged $987,592 and condo apartments $464,853 (TRREB Market Watch, September 2026).
More houses than condos sold here in September 2026: 175 detached houses and 78 condo apartments across Scarborough’s eight districts. Next door, North York detached benchmarks start at $1,010,200 and go past $3 million.
For a reverse mortgage, the percentage you can borrow is set mainly by your age, and the dollar amount by the appraised value. A Scarborough house brings a smaller dollar amount than the same house would in midtown, but for an owner who bought decades ago, it can still be a large sum of money.
The Toronto reverse mortgage calculator shows the amount for your age and your home’s value.
Who asks about reverse mortgages in Scarborough
Scarborough has the highest share of residents 65 and older of Toronto’s six former municipalities, and the highest share of homeowners. In 2021, 18.3% of residents were 65 or older, and 64.1% of households owned their home (2021 Census, counted from the City’s neighbourhood data). Owners’ own estimates of their homes averaged $847,000 on the 2021 Census, the lowest of the six.
In Ward 22 (Scarborough-Agincourt), 23.1% of residents were 65 or older in 2021, the highest share of any Toronto ward, and 37.1% of households were led by someone 65 or older. Steeles (27.3%) and Guildwood (26.5%) are among the oldest neighbourhoods in the city (City of Toronto Ward Profiles).
The reasons Scarborough owners ask are practical:
- A pension that doesn’t match the house. Money from a reverse mortgage can arrive as monthly deposits. It’s a loan, not income, so it isn’t taxed and doesn’t reduce OAS or GIS (monthly income from a reverse mortgage).
- Repairs on a house from the 1950s or 1960s. A new roof, windows or a furnace can be paid for with no required monthly mortgage payments, and so can changes like a main-floor bathroom (aging-in-place renovations).
- A mortgage still owing in retirement. A reverse mortgage can pay it off at closing, and the monthly mortgage payment stops (paying off a mortgage with a reverse mortgage).
- Family and care. Some owners want to help a grown child buy a home, or to pay for help at home in their late 80s.
A worked example: a 1950s bungalow in Scarborough at $861,700
For example, picture an illustrative widow, aged 78, in a 1950s brick bungalow in Wexford. TRREB’s September 2026 benchmark for a detached house in E04, the district that includes Wexford, is $861,700. At 78, the most she could borrow is 60% of the home’s value: $517,020 on $861,700.
Her bungalow is paid off, and she lives on CPP, OAS and a small pension. She takes $40,000 up front for a new roof and windows, plus scheduled deposits of $1,000 a month. After five years, she would have taken $100,000 of the $517,020: the $40,000 plus 60 deposits of $1,000.
The money is a loan, not income, so it isn’t taxed and doesn’t reduce her OAS or GIS. She pays interest only on the money she has taken, and it’s added to the balance instead of being paid monthly; home price growth often offsets some or all of it. Her property taxes, home insurance and upkeep stay hers to pay.
Late property taxes on a Scarborough home
Toronto adds 1.25% a month to late property taxes, or 15% a year, and the charge can’t be waived (City of Toronto). A Final Notice goes out each April for the previous year’s balance, and accounts with $100 or more owing go to a bailiff in early May.
The City can register a tax arrears certificate on the title when taxes are still owing on January 1 of the second year after they were due. The home can then be sold at a public sale if the amount isn’t paid within one year of that registration (City of Toronto Act, 2006, s. 344).
Tax arrears must be cleared at closing, and a reverse mortgage pays them out of the mortgage money, the same way it pays off an existing mortgage. After that, keeping the property taxes paid is one of your duties as the owner. Property tax arrears in Toronto explains each step of the City’s process.
The City’s relief program, for owners 65 and older with a household income of $62,000 or less, doesn’t help with arrears: it requires that no earlier years’ taxes are owing (City of Toronto). A property tax deferral and a reverse mortgage are one route or the other. Richard Hopkins, Mortgage Broker, compares both for your home and recommends the one with the best overall value for you.
Scarborough neighbourhoods and landmarks
Help is the same in every part of Scarborough. These are some of the neighbourhoods and places it covers.
- Agincourt
- L'Amoreaux
- Steeles
- Tam O'Shanter-Sullivan
- Wexford-Maryvale
- Birchcliffe-Cliffside
- Cliffcrest
- Guildwood
- West Hill
- Malvern
Landmarks
- Scarborough Bluffs
- Toronto Zoo
- Rouge National Urban Park
- Scarborough Town Centre
- Scarborough Civic Centre and Albert Campbell Square
- University of Toronto Scarborough
- Guild Park and Gardens
How the help reaches you in Scarborough
Richard Hopkins, Mortgage Broker, handles everything by email, phone and video call, and your family can be copied on every email. The appraiser comes to your house, whether it's near the Bluffs or up by Steeles. For the one in-person meeting, with your own lawyer, you can take Line 2 from Kennedy, Warden or Victoria Park station, Line 5 Eglinton from Kennedy, or drive Highway 401 (Line 3, the Scarborough RT, closed in 2023).
What Scarborough homes are worth right now
TRREB's September 2026 benchmark for a typical detached house in Scarborough goes from $861,700 in E04 (Wexford, Dorset Park, Kennedy Park) to $1,081,100 in E05 (L'Amoreaux, Steeles, Tam O'Shanter). Condo apartment benchmarks go from $369,000 in E10 (Highland Creek, West Hill) to $540,600 in E06 (Birchcliffe-Cliffside). At 65, those values mean up to about $436,000 to $546,000 on a house and $187,000 to $273,000 on a condo. At 75, they mean up to about $498,000 to $624,000 on a house and $213,000 to $312,000 on a condo.
How Scarborough homeowners use a reverse mortgage
- Monthly income from your home: Money from your home's value, paid into your bank account every month, without tax and without changing your OAS or GIS.
- Renovations to stay at home: A walk-in shower, grab bars or a stair lift, paid for from your home's value so you can stay where you are.
- Paying off your mortgage: When a renewal no longer fits a retirement income, a reverse mortgage can pay off what you owe and end the monthly mortgage payment.
- Clearing debts: A reverse mortgage can clear cards, lines of credit and property tax arrears, with no required monthly mortgage payments afterward.