TorontoReverseMortgage.ca explains reverse mortgages for Toronto homeowners 55 and older, and what a reverse mortgage in North York can provide depends on which part of North York the home is in, and what kind of home it is.
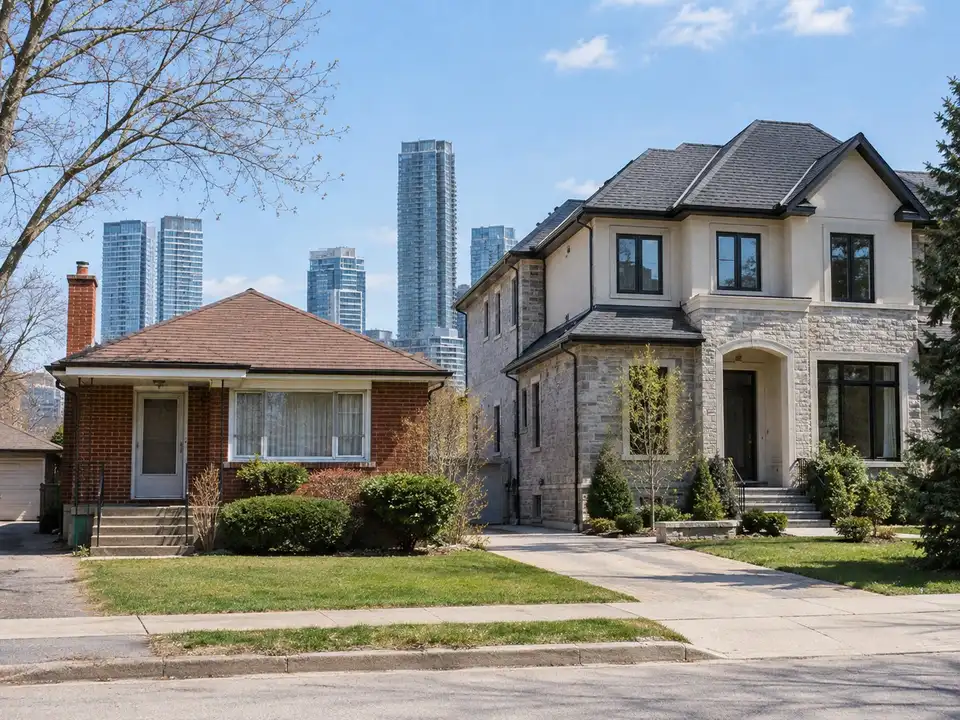
One North York street can have a 1950s bungalow next to a new house built on the lot of another, with condo towers in view. Detached benchmarks here ranged from $1,010,200 in W05 to $3,061,400 in C12 in September 2026 (TRREB Market Watch, September 2026).
This page covers what those homes mean for the amount you could borrow, who asks, and the choice some owners face when a builder offers to buy.
North York’s homes and what they mean for a reverse mortgage
North York was mostly farmland until the Second World War. It boomed in the late 1940s and 1950s, and by the 1950s and 1960s it looked like a sprawling North American suburb (Wikipedia).
In Willowdale, homes date from 1910 to the 1950s, including modest one-and-a-half-storey post-war houses. Builders began replacing them with large two-storey houses in the 1990s (Wikipedia).
The rebuilding shows in the Census. In Ward 18 (Willowdale), 20.8% of people in detached houses live in one built from 2006 to 2021, against 9.3% across Toronto. Ward 17 (Don Valley North) has seen far less: 65% live in houses built from 1961 to 1980, and only 3.9% in one built since 2006 (City of Toronto Ward Profiles).
North York also has a large condo market. Ward 18 includes the Yonge and Sheppard condo corridor, and 33.5% of its households own their condo, the second-highest share in Toronto. Across North York’s main TRREB districts (W05, C06, C07 and C12 to C15), condo apartments sold for an average of $555,771 in September 2026, against $1,823,683 for detached houses.
Detached values differ widely by district. TRREB’s benchmark was $1,010,200 in W05 (Downsview, York University Heights), $1,593,200 in C07 (Willowdale West), $1,904,000 in C14 (Willowdale East) and $3,061,400 in C12 (the Bridle Path and York Mills). Even W05 is above the detached benchmark in neighbouring York’s W03 district, $911,600.
Your age sets the percentage you can borrow, and the appraisal sets the value it applies to, counting the house and its lot together. On a rebuilding street, much of an older bungalow’s value can be in the lot, because a builder who plans to replace the house is paying for the land. The Toronto reverse mortgage calculator applies your age to your own home’s value.
Who asks about reverse mortgages in North York
North York has the two oldest neighbourhoods in Toronto. In 2021, 28.7% of Hillcrest Village residents and 28.3% of Bayview Woods-Steeles residents were 65 or older, the highest shares in the city. Across North York, 17.6% of residents were 65 or older (2021 Census, counted from the City’s neighbourhood data).
North York owners are also the most likely of Toronto’s six former municipalities to own outright: about 47% had no mortgage in 2021. The Don Valley wards are older than average too: 19.8% of residents in Ward 17 (Don Valley North) and 18.7% in Ward 16 (Don Valley East) were 65 or older, against 16.5% across Toronto.
The reasons vary with the home:
- Staying on a rebuilding street. A reverse mortgage lets you stay and keep the lot’s value for yourself and your family, instead of selling to a builder now.
- A condo mortgage at renewal. A reverse mortgage can pay off what’s owing, so the monthly mortgage payment stops (paying off a mortgage with a reverse mortgage).
- Help at home. Owners in their 80s can use the money to pay for care at home instead of moving (paying for home care).
- A child’s first home. Some parents give a child a down payment now rather than an inheritance later (a living inheritance).
A worked example: a condo near Yonge and Sheppard at $547,700
An illustrative widower, aged 70, owns a two-bedroom condo in Willowdale East, near Yonge and Sheppard. Condo apartments in C14, the TRREB district that covers Willowdale East, had an September 2026 benchmark of $547,700. At 70, he could borrow up to about 53% of that value, or about $289,000 on $547,700.
He still owes $95,000 on the condo, and his mortgage renewal is coming up. The $95,000 comes out of the $289,000, not on top of it, and it is paid off first, at closing. About $194,000 is left ($289,000 minus $95,000), and his monthly mortgage payment stops.
He leaves the $194,000 untouched for now, and it costs nothing until he takes it, for example to pay for help at home later. Interest is charged only on the $95,000. His condo fees, property taxes and home insurance are still his to pay, and the lender reviews his building and its condo corporation before approving (reverse mortgages on Toronto condos).
Selling to a builder or staying
A builder’s offer turns the lot’s value into money now, but it means leaving the street. Buying the next home in Toronto also means paying both Ontario’s and Toronto’s land transfer tax (City of Toronto).
A reverse mortgage lets you borrow against the same value and stay. The lender never owns the home. When the mortgage becomes due, you or your family decide how to sell, including to a builder, and keep everything above the balance.
The balance grows as interest is added, but home price growth often offsets some or all of it, and Canadian borrowers keep about half their equity on average. What’s typically called the no negative equity guarantee means you never owe more than the home’s fair market value on the day the mortgage comes due, as long as taxes, insurance and upkeep are kept up.
Neither route fits everyone. Richard Hopkins, Mortgage Broker, weighs staying against selling with you, and his recommendation is based on your situation, reverse mortgage or not. What downsizing in Toronto costs sets out the price of a move.
North York neighbourhoods and landmarks
Help is the same in every part of North York. These are some of the neighbourhoods and places it covers.
- Willowdale
- Don Mills
- Bayview Village
- Bathurst Manor
- York Mills
- Hillcrest Village
- Newtonbrook
- Downsview
- York University Heights
- Victoria Village
Landmarks
- Yorkdale Shopping Centre
- Fairview Mall
- North York Civic Centre and Mel Lastman Square
- Downsview Park
- The Village at Black Creek
- York University
- Edwards Gardens
- North York General Hospital
How the help reaches you in North York
Richard Hopkins, Mortgage Broker, looks after North York homeowners by email, phone and video call, and a son or daughter can join on a three-way call. An appraiser visits the house or condo to confirm its value. For the one meeting in person, with your own lawyer, North York has Line 1 on Yonge and on the Spadina side (Yorkdale, Wilson, Sheppard West), all of Line 4 Sheppard, Line 6 Finch West since December 7, 2025, and Highways 401, 400 and 404.
What North York homes are worth right now
In TRREB's September 2026 report, North York's detached benchmark ranged from $1,010,200 in W05 (Downsview, York University Heights) to $3,061,400 in C12 (the Bridle Path, York Mills), with $1,904,000 in C14 (Willowdale East) in between. For condo apartments, the benchmark was $443,000 in W05, $547,700 in C14 near Yonge and Sheppard and $1,045,200 in C12. At 65, a W05 detached house means up to about $511,000 and a C14 condo about $277,000. At 75, the same two homes mean up to about $583,000 and $316,000.
How North York homeowners use a reverse mortgage
- Reverse mortgages on Toronto condos: Every lender accepts a standard condo, but each one also reviews your building, so the same Toronto unit can get different answers.
- Paying off your mortgage: When a renewal no longer fits a retirement income, a reverse mortgage can pay off what you owe and end the monthly mortgage payment.
- Helping your children buy a home: Give part of an inheritance now, while you can see it help, and keep living in your own home.
- Paying for care at home: Public home care is free if you qualify, and monthly deposits from your home's value can pay for the extra hours.
- Buying a condo with a reverse mortgage: A reverse mortgage can pay part of the price of your next Toronto condo, so more of your house sale stays in the bank.