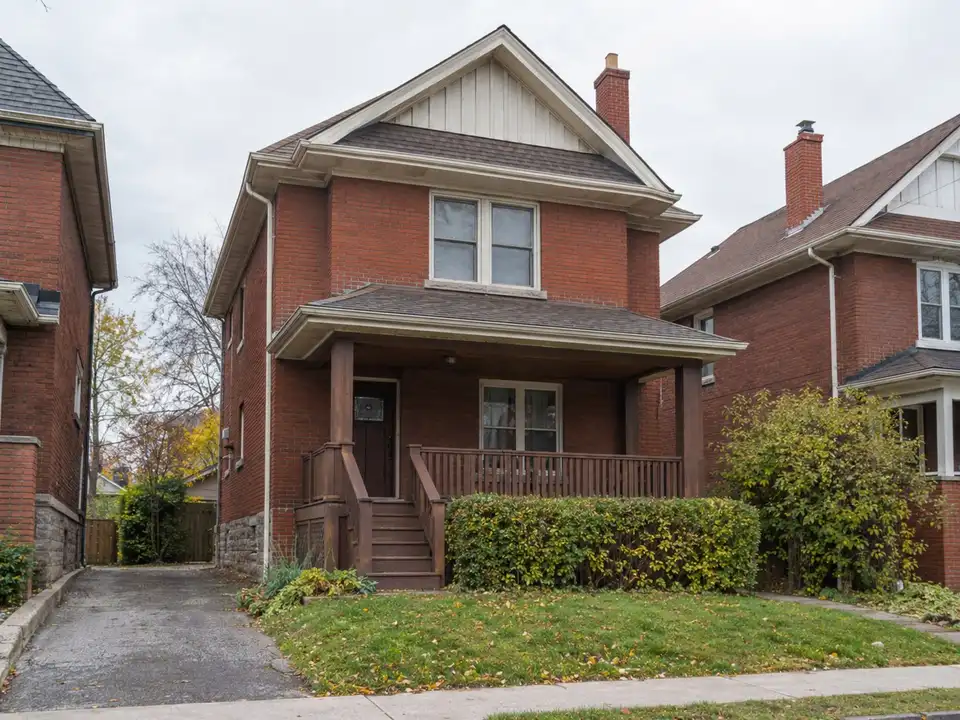
TorontoReverseMortgage.ca describes how a reverse mortgage in York works for homeowners 55 and older in the former City of York, not York Region. This York is inside Toronto: it was a city of its own until it merged into today’s Toronto in 1998.
Its neighbourhoods include Weston, Mount Dennis, Fairbank and Oakwood Village. York has some of the lowest detached prices west of Yonge Street, and lower incomes than most of the city. Both shape which kind of help fits, from City tax relief to a reverse mortgage.
York’s homes and what they mean for a reverse mortgage
Oakwood Village and Humewood-Cedarvale were developed in the 1910s, and York’s southern neighbourhoods were built up in the 1920s. About 46.7% of York’s homes were built in 1960 or earlier, second only to East York among Toronto’s six former cities.
That 2021 Census figure groups the City’s neighbourhood profiles by the old borders, so treat it as a close estimate (City of Toronto Neighbourhood Profiles, 2021 Census).
In Ward 5 (York South-Weston), 22% of people in detached houses live in one built before 1946, and 34% in one built from 1946 to 1960 (City of Toronto Ward Profiles, 2021 Census).
York’s detached prices are among the lowest west of Yonge Street. W03’s detached benchmark (TRREB’s price for a typical house) was $911,600 in September 2026, and W04’s was $1,014,100.
Of all TRREB districts west of Yonge, only W10 in north Etobicoke was lower, at $855,100 (TRREB Market Watch, September 2026).
These districts are a close fit, not an exact one. W04 also takes in Maple Leaf, Rustic and Yorkdale-Glen Park, which belong to North York, and TRREB counts Humewood-Cedarvale with the midtown district C03.
For a reverse mortgage, a lower value means a smaller dollar amount at the same age, not different rules. Interest rates are the same across Ontario, so only the dollar amount changes with the value.
York also gained rapid transit this year. Line 5 Eglinton opened on February 8, 2026, and its Mount Dennis, Keelesdale, Caledonia, Fairbank and Oakwood stations are the former city’s first rapid transit stops (City of Toronto). At Mount Dennis, riders connect to the GO Kitchener line and the UP Express.
Who asks about reverse mortgages in York
About 16.1% of York residents were 65 or older in 2021, on the same close-estimate basis. Ward 5 (York South-Weston), which covers most of the former city, had a median household income of $72,000 in 2020, the second-lowest of Toronto’s 25 wards (City of Toronto Ward Profiles, 2021 Census).
Among Ward 5’s seniors, 19.5% lived on a low income in 2020, by Statistics Canada’s after-tax measure. Only 48.1% of the ward’s households owned their home.
The questions in York can start with a mortgage still owing at retirement: about 57.3% of York owners still had one in 2021, on the same close-estimate basis. Others start with repairs on an older house, or a pension that doesn’t cover monthly costs.
A reverse mortgage can pay off the mortgage, pay for repairs that help you stay, or add monthly income.
A worked example: a two-storey house in York at $1,014,100
For example, an illustrative couple aged 65 and 69 owns a two-storey house in Mount Dennis, near the new Line 5 station, with no mortgage left. It is valued at $1,014,100, TRREB’s September 2026 detached benchmark for W04. Using the younger owner’s age of 65, they could borrow up to about 50.5% of the value, or about $512,600.
They owe $38,000 on credit cards and $22,000 on a car loan, and the monthly payments on those debts total about $1,500. They take $60,000 to pay off both debts, and about $452,600 of room stays unused, with no interest charged on it.
The $1,500 a month those debts cost is now theirs to keep for daily costs, and they have no required monthly mortgage payments. Property taxes, home insurance and upkeep are still theirs to pay. Interest adds to the $60,000 over time, but home price growth often offsets some or all of it.
City tax relief that may come first
If your household income is $62,000 or less, the City of Toronto’s relief program may help before any borrowing (City of Toronto).
At 65 or older, if you meet its other conditions, it cancels the year’s property tax increase when your home’s assessment is below $975,000, and assessments still use 2016 values (MPAC).
The City can instead defer the increase, with no assessment limit, and the deferred amount becomes due when the home is sold or transferred. The deadline for 2026 is November 2, 2026, and you reapply every year.
These programs cover the yearly increase, not the whole tax bill. If you need more than that, a property tax deferral and a reverse mortgage are one route or the other; see how Toronto’s property tax deferral works.
York neighbourhoods and landmarks
Help is the same in every part of York. These are some of the neighbourhoods and places it covers.
- Weston
- Mount Dennis
- Fairbank
- Silverthorn
- Oakwood Village
- Humewood-Cedarvale
- Baby Point
- Caledonia
- Rockcliffe-Smythe
- Keelesdale
Landmarks
- York Civic Centre
- Weston Road main street in Weston village
- Mount Dennis station, on the former Kodak campus
- Lambton House
- Weston GO and UP Express station
- Fairbank Memorial Park
How the help reaches you in York
Richard Hopkins, Mortgage Broker, helps York homeowners by email, phone and video call, with family copied on every email if you like. An appraiser visits the home. For the in-person appointment with your own lawyer, Line 5 Eglinton links York's five stations to Line 1 at Cedarvale and Eglinton, and the UP Express stops at Weston and Mount Dennis on its way to Union Station.
What York homes are worth right now
TRREB's September 2026 benchmarks (its prices for a typical home) were $911,600 for a detached house in W03 and $1,014,100 in W04, and $490,100 and $489,000 for a condo apartment. W04 is only an approximation for York, since it also counts Maple Leaf, Rustic and Yorkdale-Glen Park in North York. At 65, up to 50.55% of the value means about $460,800 on a W03 house and about $512,600 on a W04 house; at 75, up to 57.75% means about $526,400 and about $585,600.
Source: TRREB Market Watch, September 2026 (MLS® Home Price Index benchmarks)
How York homeowners use a reverse mortgage
- Monthly income from your home: Money from your home's value, paid into your bank account every month, without tax and without changing your OAS or GIS.
- Paying off your mortgage: When a renewal no longer fits a retirement income, a reverse mortgage can pay off what you owe and end the monthly mortgage payment.
- Renovations to stay at home: A walk-in shower, grab bars or a stair lift, paid for from your home's value so you can stay where you are.
- Clearing debts: A reverse mortgage can clear cards, lines of credit and property tax arrears, with no required monthly mortgage payments afterward.