TorontoReverseMortgage.ca sets out how reverse mortgages work for Toronto homeowners 55 and older, including owners in every part of Etobicoke, from Long Branch to Rexdale.
A reverse mortgage in Etobicoke follows the same rules on an English-inspired house in the Kingsway, a post-war split-level in Humber Valley Village, a house in Rexdale or a condo at Humber Bay Shores. The dollar amount can differ by hundreds of thousands of dollars from one to another.
The figures below come from TRREB’s September 2026 report for Etobicoke’s five districts, W06 to W10, and the 2021 Census for Wards 1, 2 and 3.
Etobicoke’s homes and what they mean for a reverse mortgage
Etobicoke’s residential streets are mainly single-family houses, with high-rise condos near the Humber River in the south (Wikipedia).
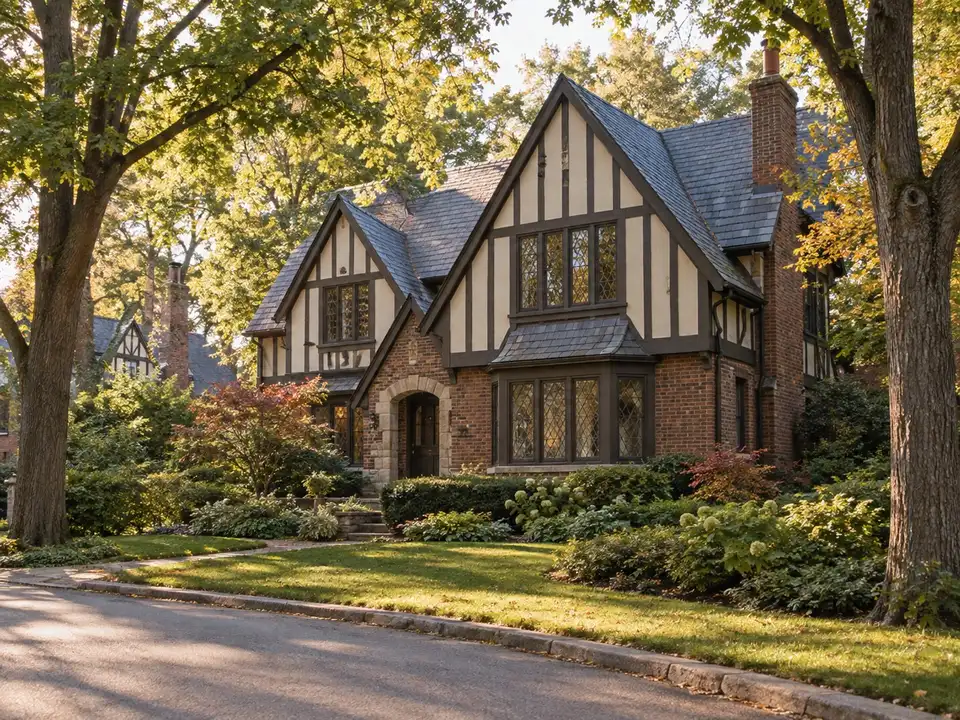
The Kingsway was developed by Robert Home Smith from the early 1900s and built out through the 1920s. Most of its homes were designed in the Arts and Crafts style, and the Tudor Revival Old Mill inspired much of the area’s English look (Wikipedia).
Humber Valley Village, next door, was built from the mid-1930s to the 1960s. Its styles go from Georgian and Tudor to English cottages, ranch bungalows and split-levels (Wikipedia).
Most Etobicoke houses were built after the Second World War. In Ward 3 (Etobicoke-Lakeshore), 43% of people in detached houses live in one built from 1946 to 1960, and 26% in one built before 1946. In Ward 1 (Etobicoke North), about 70% live in houses built from 1946 to 1980 (City of Toronto Ward Profiles).
Prices differ widely across Etobicoke’s five TRREB districts. The detached benchmark was $855,100 in W10 (Rexdale, Thistletown), $1,155,500 in W06 (Mimico, New Toronto, Long Branch, Alderwood), $1,213,200 in W09 (Humber Heights, Richview) and $1,623,000 in W08 (the Kingsway, Islington, Humber Valley) (TRREB Market Watch, September 2026).
Across all five districts, detached houses sold for an average of $1,523,088 in September 2026, and condo apartments for $581,800. Condos were 121 of Etobicoke’s 275 sales that month, and W06 condo apartments near the lake averaged $640,225.
A reverse mortgage uses a percentage of the appraised value, and your age decides the percentage. W08’s detached benchmark is almost double W10’s, so two owners of the same age, one in the Kingsway and one in Rexdale, can qualify for very different amounts. Try your own house in the Toronto reverse mortgage calculator.
Who asks about reverse mortgages in Etobicoke
Etobicoke Centre (Ward 2) is the second-oldest ward in Toronto. In 2021, 21.4% of its residents were 65 or older, and 35.2% of its households were led by someone 65 or older (City of Toronto Ward Profiles). Markland Wood (26.7%) and Kingsway South (23.3%) are among the city’s oldest neighbourhoods, while Etobicoke North (15.6%) and Etobicoke-Lakeshore (16.9%) are younger.
Seniors in Etobicoke Centre are less likely to live on a low income. Ward 2 is 67.4% owner-occupied, and only 9.6% of its seniors lived on a low income in 2020, against 16.9% across Toronto. Across Etobicoke, about 44% of owners had no mortgage in 2021 (counted from the City’s neighbourhood data).
For many owners like these, the question is less about paying bills and more about how to stay without selling:
- An older house that needs changes. A main-floor bathroom, a stair lift or wider doorways can be paid for with no required monthly mortgage payments (aging-in-place renovations).
- A first home for a son or daughter. A reverse mortgage can fund a down payment while you’re here to see it used (a living inheritance).
- A move to the lake. A reverse mortgage can also pay for part of a condo purchase in Mimico or Humber Bay Shores (buying a condo with a reverse mortgage).
- One spouse needing care. Nothing changes while a spouse who is also a borrower still lives in the home (reverse mortgages and long-term care).
A worked example: a 1960s split-level in Etobicoke at $1,623,000
Consider an illustrative couple, aged 60 and 64, who own a 1960s split-level in Humber Valley Village. Their neighbourhood is in TRREB’s W08 district, where the September 2026 detached benchmark was $1,623,000. The younger spouse is 60, so the most they could borrow is about 48.5% of that value, or about $788,000 on $1,623,000.
Their house is paid off. They want $150,000 toward their daughter’s first home and $60,000 for new windows and a furnace, so they take $210,000. The other $578,000 of the $788,000 stays untouched and costs no interest.
The $210,000 is a loan, not income, so it isn’t taxed. Interest is added to the balance, but home price growth often offsets some or all of it, and Canadian borrowers keep about half their equity on average. Some lenders use a combined age for a couple instead of the younger spouse’s age, which can change the amount by tens of thousands of dollars.
Tax credits for adapting an older Etobicoke house
Two federal tax credits can give back part of the cost of adapting a home for an older person. The Home Accessibility Tax Credit covers up to $20,000 a year of eligible work for a person 65 or older, worth up to $3,000, claimed on line 31285 of the tax return (Canada Revenue Agency).
The Multigenerational Home Renovation Tax Credit returns 15% of up to $50,000 of work, or up to $7,500, for building a self-contained second unit so a person 65 or older can live with a relative. You claim it on line 45355 (Canada Revenue Agency).
A reverse mortgage can pay for the work up front, and these credits give back part of the cost at tax time. Both credits have conditions, so keep your receipts and check the rules before the work starts. The reverse mortgage assessment helps you check whether a reverse mortgage fits before you plan the work.
Etobicoke neighbourhoods and landmarks
Help is the same in every part of Etobicoke. These are some of the neighbourhoods and places it covers.
- The Kingsway
- Humber Valley Village
- Islington
- Markland Wood
- Princess-Rosethorn
- Eringate-Centennial-West Deane
- Mimico
- New Toronto
- Long Branch
- Rexdale
Landmarks
- James Gardens
- Centennial Park
- Colonel Samuel Smith Park
- Humber Polytechnic
- Montgomery's Inn
- Etobicoke Civic Centre
How the help reaches you in Etobicoke
Everything with Richard Hopkins, Mortgage Broker, is done by email, phone and video call, with your family copied on every email if you like. The appraiser comes to the property, whether it's a Kingsway house or a condo at Humber Bay Shores. For the in-person meeting with your own lawyer, Line 2 stops at Kipling, Islington, Royal York and Old Mill, Line 6 Finch West ends at Humber College, and the Gardiner, the QEW and Highway 427 all cross Etobicoke.
What Etobicoke homes are worth right now
Etobicoke's detached benchmark was $855,100 in W10 (Rexdale, Thistletown) and $1,623,000 in W08 (the Kingsway, Islington, Humber Valley) in TRREB's September 2026 report. Condo apartments had benchmarks of $408,400 in W10 and $607,800 in W06 (Mimico, New Toronto, Long Branch). For a 65-year-old, that is up to about $432,000 to $820,000 on a house, or $206,000 to $307,000 on a condo. For a 75-year-old, it rises to about $494,000 to $937,000 on a house, or $236,000 to $351,000 on a condo.
How Etobicoke homeowners use a reverse mortgage
- Renovations to stay at home: A walk-in shower, grab bars or a stair lift, paid for from your home's value so you can stay where you are.
- Helping your children buy a home: Give part of an inheritance now, while you can see it help, and keep living in your own home.
- Buying a condo with a reverse mortgage: A reverse mortgage can pay part of the price of your next Toronto condo, so more of your house sale stays in the bank.
- Reverse mortgages on Toronto condos: Every lender accepts a standard condo, but each one also reviews your building, so the same Toronto unit can get different answers.
- Paying for care at home: Public home care is free if you qualify, and monthly deposits from your home's value can pay for the extra hours.